
What a date-of-death appraisal is
A date-of-death appraisal is a retrospective appraisal with an effective date matching the property owner's date of death. The effective date is the date of death, not the day of the inspection. The inspection may occur after the date of death, but the analysis is tied to that historical date: comparable sales and market conditions are studied as they stood then, not as they stand today.
That date matters because Pennsylvania requires real estate on the inheritance tax return to be reported at fair market value as of the date of death. PA Revenue's REV-1502 instructions define fair market value as the price a willing buyer and a willing seller would agree on, with neither one compelled to act and both reasonably informed. Unlike the federal system, Pennsylvania has no six-month alternate valuation date (REV-1500 instructions).
Pennsylvania inheritance tax: the dates that matter
The 5% discount
A 5 percent discount applies to tax paid within three months of death. Chester County's Register of Wills packet stresses that the period is "three (3) months, NOT 90 days, from date of death."
File and pay
The return must be filed, and the tax paid, within nine months after death. An extension to file does not extend the time to pay.
Register of Wills
The return is filed with the county Register of Wills, which acts as the Commonwealth's agent for filing and paying inheritance tax.
Sources: PA Revenue's inheritance tax page, REV-1500 instructions, and the Chester County Register of Wills packet (FAQ). Chester County's checklist also lists filing the estate inventory with the Register of Wills within nine months; other counties may word this differently.
If the family is aiming for the three-month discount, mention it when you call so the appraisal can be scheduled with that date in mind. No appraiser can promise a particular date, but knowing it up front helps.
Pennsylvania inheritance tax rates
| Who receives the house | Rate |
|---|---|
| Surviving spouse | 0% |
| Parent, from a child aged 21 or younger | 0% |
| Children, grandchildren and other lineal heirs | 4.5% |
| Brothers and sisters | 12% |
| Other heirs (except charities and exempt institutions) | 15% |
Property owned jointly between spouses is exempt (PA Revenue). Real estate held by spouses as tenants by the entireties, or as joint tenants with right of survivorship, for more than one year before death is also exempt (REV-1502 instructions).
Three ways Pennsylvania lets you value the house
An appraisal is not always required. PA Revenue's REV-1502 instructions list three methods for valuing real estate on the return:
Sale price
Allowed only if the house sold within 15 months of death, and it must be the gross sale price.
Appraisal
A certified appraisal of fair market value as of the date of death.
Assessed value × CLR
The county tax assessment multiplied by the common level ratio (CLR) factor.
Whichever method is used, the return should include the tax assessment notice, certified appraisal or settlement sheet that supports it.
How assessed value × CLR works
The CLR factors are the reciprocals of each county's common level ratio, based on State Tax Equalization Board sales data. Here are the factors published in July 2026 for the Pennsylvania areas ProValue serves (PA Revenue CLR factor table):
| County | CLR factor (published July 2026) |
|---|---|
| Chester | 3.27 |
| Montgomery | 3.36 |
| Delaware | 1.83 |
| Lancaster | 2.00 |
| Berks | 3.12 |
| Philadelphia | 1.06 through Dec. 31, 2026; then 1.00 |
Arithmetic example: a Chester County house assessed at $100,000 × 3.27 = $327,000.
The published table is labeled for realty transfer tax documents accepted July 1, 2026 through June 30, 2027. Confirm with your attorney or CPA which factor applies to your date of death.
When an appraisal is the better choice
The assessed-value method is legal, and sometimes it is enough. A county assessment is not the same as market value, though, and the CLR factor is a county-wide figure that does not look at the house itself. These are common situations where families choose an appraisal:
The house is sold to a family member, or to someone involved with the estate
Revenue requires an appraisal or other documentary evidence of fair market value if the real estate was sold to a family member or anyone associated with administering the estate (REV-1502 instructions).
Heirs may sell later (step-up in basis)
An heir's basis in inherited property is generally its fair market value on the date of death (IRS FAQ). If no estate tax Schedule A was issued, IRS Publication 551 says basis can be determined using the appraised value at the date of death for state inheritance tax purposes. A lower date-of-death value means less Pennsylvania inheritance tax, but it can also mean a lower starting basis for the heirs. Your CPA can weigh this.
Heirs disagree, or one heir is buying out the others
An independent appraisal gives everyone the same documented number to work from.
Selling the house
If the estate sells within 15 months of death, the gross sale price can be used on the Pennsylvania return, so an appraisal may not be needed for that purpose. It can still help with pricing the house or with the heirs' records.
Larger estates and the federal estate tax
A federal estate tax return (Form 706) is required only when the gross estate, plus adjusted taxable gifts and specific gift tax exemption, exceeds the filing threshold: $15,000,000 for 2026 deaths (IRS estate tax page). Pennsylvania has no estate tax for deaths on or after January 1, 2005; an estate that files Form 706 must also file a copy with Pennsylvania (REV-229).
How a past-date (retrospective) appraisal works
- Confirm the assignment. Property address, intended use, intended users and the effective date (the date of death).
- Inspect the property. The inspection may occur weeks or months after the date of death.
- Research the date of death. Comparable sales and market conditions are analyzed as of the date of death, not today's market alone.
- Deliver the report. A USPAP-compliant appraisal report with the value as of the date of death.
If the house changed after the death, such as repairs, renovations or a cleanout, note those changes so they can be addressed in the scope of work.
The inspection, including vacant houses and cleanouts
If the house is vacant, access needs to be arranged before the inspection. Mention it when you call so a time can be set. If the house is partly cleaned out or in the middle of repairs, mention that too; either way, the value is developed as of the date of death.
Helpful to have ready:
- The date of death
- The property address (and parcel number, if handy)
- Who will rely on the report: executor, attorney or accountant
- Any attorney or CPA instructions
- Dated photos, the last listing, or contractor invoices that show the house before any changes
The fee is $600 base per appraisal; more complex cases (including multi-property estates) are quoted individually.
What the report includes
- Market value opinion as of the requested historical date
- Comparable sales research appropriate to that effective date
- Neighborhood and market commentary
- Photos, maps, and supporting documentation
- Clear identification of the intended use, intended users, and effective date
The report is delivered for the estate's attorney or accountant to attach to the return, as the REV-1502 instructions ask for the certified appraisal used.
Fee and turnaround
The fee is $600 base per appraisal; more complex cases, including multi-property estates, are quoted individually. Turnaround is 5 business days from the inspection. Ian will confirm the fee for your property when you call.
The appraisal is for valuation purposes only and is not legal, tax, or estate advice.
Areas served
Date-of-death appraisals are offered in the areas below. Ian works with homeowners, executors, attorneys, and accountants throughout Southeastern Pennsylvania, Philadelphia and New Castle County, Delaware.
Delaware estates
Delaware repealed its estate tax for deaths after December 31, 2017 (Delaware Code Title 30, Chapter 15). So in Delaware, a date-of-death appraisal is mainly used to document the heirs' step-up in basis, to support a sale or a buyout among heirs, and for the federal estate tax return if the estate is large enough to need one.
For Pennsylvania estates that include Delaware property: real estate outside Pennsylvania is exempt from Pennsylvania inheritance tax unless it was under contract to sell before death (REV-1502 instructions). For Delaware legal questions, talk to your estate attorney.
About Ian Ritter
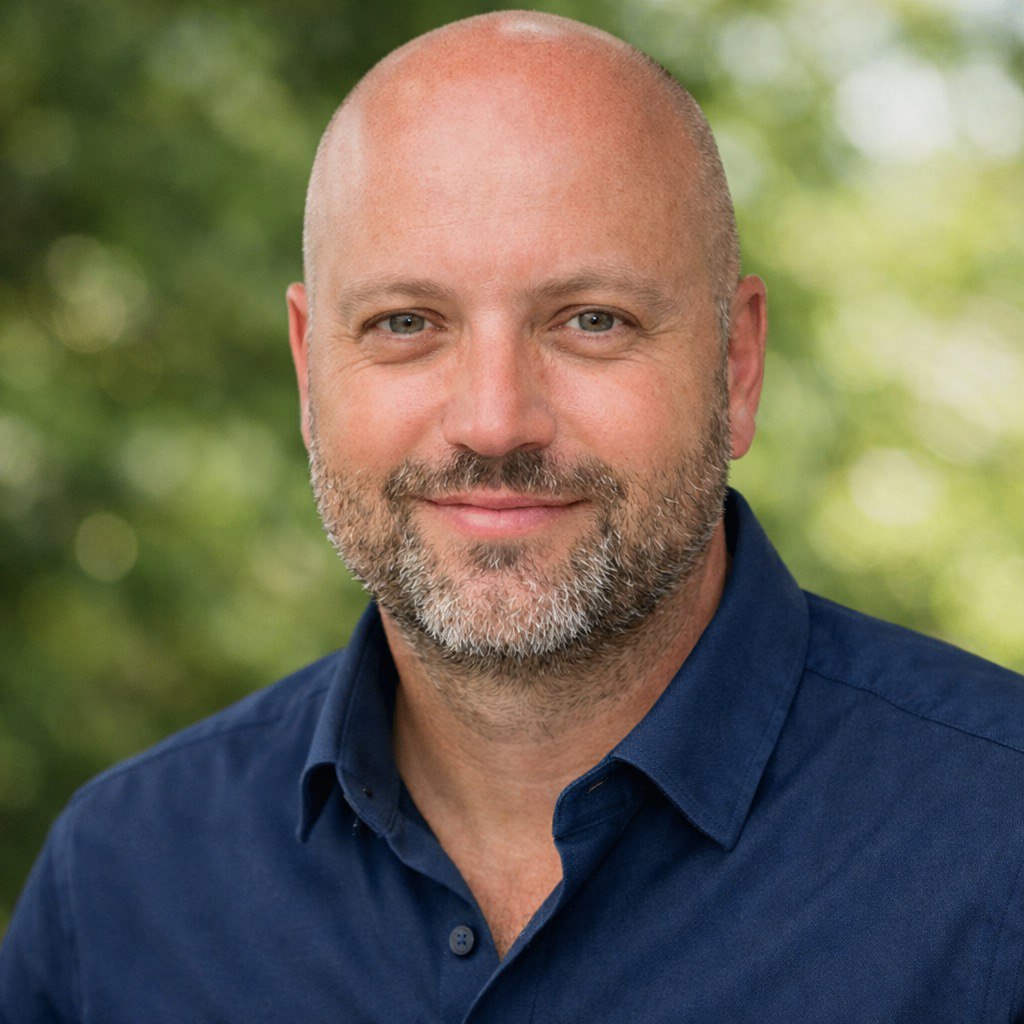
Ian Ritter is a Certified Residential Appraiser and the founder of ProValue Appraisal Services LLC, based in Downingtown, PA. He has been appraising since 2019 and works directly with executors, estate attorneys, accountants and families.
Common questions
What is a date-of-death appraisal?
A date-of-death appraisal is a retrospective appraisal. It estimates what a home was worth on the day the owner died, not today. The inspection can happen weeks or months later, but the sales and market conditions are studied as of the date of death, which is the value Pennsylvania uses for inheritance tax.
What does "date of death" mean for the appraisal?
The date of death is the appraisal's effective date. The value reflects the sales and market conditions on that day and the home's condition on that day, even if the inspection happens later. Pennsylvania values real estate as of the date of death, with no alternate valuation date, so tell the appraiser about any later repairs or cleanouts.
How soon after a death should the appraisal be done?
Because the value is fixed at the date of death, the appraisal can be done later. Timing follows the estate's deadlines: Pennsylvania inheritance tax is due nine months after death, with a 5 percent discount if paid within three months. Sooner is easier, before the house is cleaned out, repaired, sold or distributed. Ask your attorney or CPA about timing.
Do I need an appraisal for Pennsylvania inheritance tax?
Not always. Pennsylvania accepts three ways to value real estate on the inheritance tax return: the gross sale price if the house sold within 15 months of death, an appraisal, or the county assessed value multiplied by the common level ratio factor. If a family member bought the house, an appraisal or other proof of value is required.
When is Pennsylvania inheritance tax due?
Pennsylvania inheritance tax is due nine months after the date of death, and the return is filed with the county Register of Wills. Tax paid within three months of death earns a 5 percent discount. An extension to file the return does not extend the time to pay. Your attorney or accountant can confirm your estate's dates.
Can I use the county assessed value instead of an appraisal?
Yes, for the Pennsylvania return. Revenue allows the county assessed value multiplied by the common level ratio factor, with the assessment notice attached. The factor is a county-wide figure based on State Tax Equalization Board sales data, so it does not look at the house itself. Ask your attorney or CPA which method fits your estate.
How does a date-of-death value affect the heirs' tax basis?
An heir's basis in an inherited home is generally its fair market value on the date of death. IRS Publication 551 says that if no estate tax Schedule A was issued, basis can be determined using the appraised value at the date of death used for state inheritance tax. Your CPA can explain what it means for a sale.
Does the estate have to file a federal estate tax return?
Only if the gross estate, plus certain lifetime gifts, is more than the IRS filing threshold, which is $15,000,000 for deaths in 2026. Pennsylvania has had no separate estate tax for deaths since January 1, 2005. Real estate is still valued as of the date of death on the Pennsylvania inheritance tax return.
Who orders a date-of-death appraisal, and what should I have ready?
Usually the estate's personal representative, meaning the executor or administrator, or the estate's attorney. Helpful to have: the date of death, the property address, letters testamentary or letters of administration if granted, any changes since the date of death, and any prior appraisal or the deed. If the house is vacant, access needs to be arranged before the inspection.
How much does a date-of-death appraisal cost, and how long does it take?
ProValue's base fee is $600 per appraisal; more complex cases, including multi-property estates, are quoted individually. Turnaround is 5 business days from the inspection. To get started, call Ian Ritter at (484) 886-8689 or email provalueappraisal@gmail.com with the property address, the date of death, and who will rely on the report.
Which areas do you serve for date-of-death appraisals?
Date-of-death appraisals are offered in Pennsylvania for Chester, Montgomery, Delaware, Lancaster and Berks Counties and Philadelphia, and in New Castle County, Delaware. Ian Ritter is a Certified Residential Appraiser licensed in both states: Pennsylvania (RL140354) and Delaware (X2-0010765).
This page summarizes published government guidance and is not legal or tax advice. Talk to your estate attorney or CPA about which valuation method, CLR factor or filing approach fits your estate.